January 21, 2026 · StrivePoint Advisors
Mortgage banking and business lending: David Wallace of StrivePoint Advisors on working as a broker
with David Wallace, Co-Founder — StrivePoint Advisors
Operating as a mortgage broker can mean more loan options and less pressure than traditional mortgage banking, says David Wallace, co-founder of StrivePoint Advisors, who has worked in the field since 1993. With experience dating back to 1993, Wallace emphasizes the advantages of operating as a mortgage broker, including flexibility in loan options and reduced pressure compared to traditional mortgage banking. He also highlights his commitment to ethical practices and helping small businesses secure financing.
David Wallace Discusses Mortgage Banking and Business Lending Strategies
David Wallace Discusses Mortgage Banking and Business Lending Strategies
David Wallace, co-founder and president of StrivePoint Advisors, discussed his extensive background in finance and the evolving landscape of mortgage banking and business lending during a recent episode of the Phoenix Business Brief Podcast. Wallace, who has worked in the finance sector since 1993, shared insights on the advantages of operating as a mortgage broker and the current state of the housing market.
Wallace began his career at Charles Schwab in strategic planning before transitioning to mortgage banking. He played a pivotal role in the sale of American Mortgage Network to Wachovia in 2005. Following the merger of Wachovia and Wells Fargo, Wallace continued to navigate the complexities of the mortgage industry, eventually founding StrivePoint Advisors, which focuses on residential mortgages and business lending.
At StrivePoint Advisors, Wallace has shifted from traditional mortgage banking to a brokerage model. He explained that this transition has allowed him to better serve clients by offering a wider range of options. "I can shop the loan to anybody I want," he said, emphasizing the flexibility brokers have in finding the best pricing and terms for borrowers.
The difference between mortgage banks and brokers lies in the underwriting process. Wallace noted that mortgage banks must undergo rigorous audits and assume significant risks, such as repurchase liability if loans are not accepted by secondary market buyers. In contrast, brokers like StrivePoint Advisors do not take on these liabilities, which reduces pressure and allows for a more client-focused approach.
Wallace highlighted the current market conditions for first-time homebuyers, particularly younger generations who may feel discouraged by rising prices. He noted that many programs exist to assist these buyers, making homeownership more attainable. "If you're paying $3,000 a month in rent, how much are you going to have to pay to buy your house?" he asked, encouraging potential buyers to consider the long-term benefits of investing in property.
In addition to residential mortgages, StrivePoint Advisors also provides business lending services, including Small Business Administration (SBA) loans. Wallace shared a recent success story of helping a commercial cleaning company refinance its debt and acquire two competitors, significantly reducing its monthly debt service.
Wallace remains optimistic about the future of the housing market, despite concerns about interest rates. He advised borrowers not to wait for rates to drop to historical lows, suggesting that current rates around 5% are still attractive. "Real estate is one of the best investments you can make over the last 70 years," he stated.
As he reflects on his career, Wallace emphasizes the importance of ethics in business. He aims to provide transparent and reasonable financing options for clients, distinguishing himself from less scrupulous operators in the industry. "I'm just a straight shooter," he said, reinforcing his commitment to integrity in lending practices.
For those considering starting a business, Wallace encourages aspiring entrepreneurs to explore the myriad opportunities available. He noted that many businesses, regardless of their nature, are actively seeking capital to grow. "There's no shortage in businesses starting up," he said, highlighting the potential for success in various sectors.
Wallace's insights underscore the dynamic nature of the mortgage and business lending industries. As StrivePoint Advisors continues to navigate these challenges, Wallace remains dedicated to helping clients achieve their financial goals through informed and ethical lending practices.
Interview Q&A
Q&A: David Wallace Discusses Mortgage Banking and Business Lending Strategies
David Wallace Discusses Mortgage Banking and Business Lending Strategies
Q: Can you tell us about your background and experience in the finance industry?
A: I am the president of StrivePoint Advisors and have been in the finance industry since 1993. I started at Charles Schwab in strategic planning from 1998 to 2003, then moved to American Mortgage Network to help sell the company. We sold it to Wachovia in December 2005. After the crash, I worked with several mortgage companies and now focus on residential mortgages and business lending.
Q: How has your shift from mortgage banking executive to mortgage broker affected your career satisfaction?
A: I find more satisfaction in interacting with people and being on the front lines. While I still handle back-office responsibilities as CFO and president, I enjoy the flexibility and lower pressure of being a broker compared to my previous roles in mortgage banking.
Q: What are the key differences between being a mortgage banker and a broker?
A: As a mortgage banker, you handle underwriting and take on repurchase liability, which adds significant pressure. As a broker, I can shop loans to various lenders and avoid the risks associated with underwriting, allowing for a more enjoyable and less stressful work environment.
Q: How does being a broker benefit your customers?
A: I can find the best loan options for my clients by shopping around among different lenders. This allows borrowers to access better pricing and a smoother process tailored to their specific needs.
Q: What sets StrivePoint Advisors apart from other brokers?
A: StrivePoint Advisors offers access to a range of loan options, including hard money loans, which not all brokers have. My partner, Brian Taylor, and I bring extensive experience in finance and lending, ensuring that we can provide knowledgeable guidance to our clients.
Q: Are there any current trends in the mortgage market that you find positive?
A: The Trump administration's commitment to lowering housing costs through agency bond purchases is a positive step. However, I advise borrowers not to wait for rates to drop to 3%, as that may never happen. Current rates around 5% are still attractive for homebuyers.
Q: How do you address concerns from younger generations about homeownership?
A: I work with first-time homebuyers to help them understand the financial benefits of owning a home versus renting. Programs exist to assist with minimal down payments, making homeownership more accessible.
Q: What advice do you have for those considering starting a new business?
A: There are numerous opportunities for new businesses, and many are actively seeking capital. I recently helped a commercial cleaning company reduce its debt service and acquire competitors, demonstrating that even non-tech businesses can thrive with the right financing.
Q: Can you share an example of how you've helped a business with financing?
A: I assisted a commercial cleaning company in refinancing high-interest debt and acquiring two competitors. This reduced their monthly debt service from $22,000 to $8,000, significantly improving their cash flow and overall business performance.
Q: What is your approach to ethics in business?
A: Ethics are paramount in my work. I prioritize transparency and integrity, ensuring that my clients receive honest and straightforward advice regarding their financing options.
Q: Any final thoughts for potential clients?
A: If you're looking for a reliable advisor who prioritizes ethics and straightforward communication, I encourage you to reach out to me. I can provide valuable insights into both business and residential financing.
Key takeaways
- “I started to have a lot more fun, you know, selling and being on the front lines.”
- “The pressure relief is a lot higher on the broker side than it is on the banking side.”
- “Don't wait for rates to go down to 3%. In my opinion, rates should never have been at 3%.”
- “If you're gonna wait around for rates to go down to 4%, it might never happen.”
- “I don't think there's any shortage in businesses starting up. There's opportunities abound.”
- “I'm just a straight shooter. I'm gonna give you exactly what it is.”
About the guest
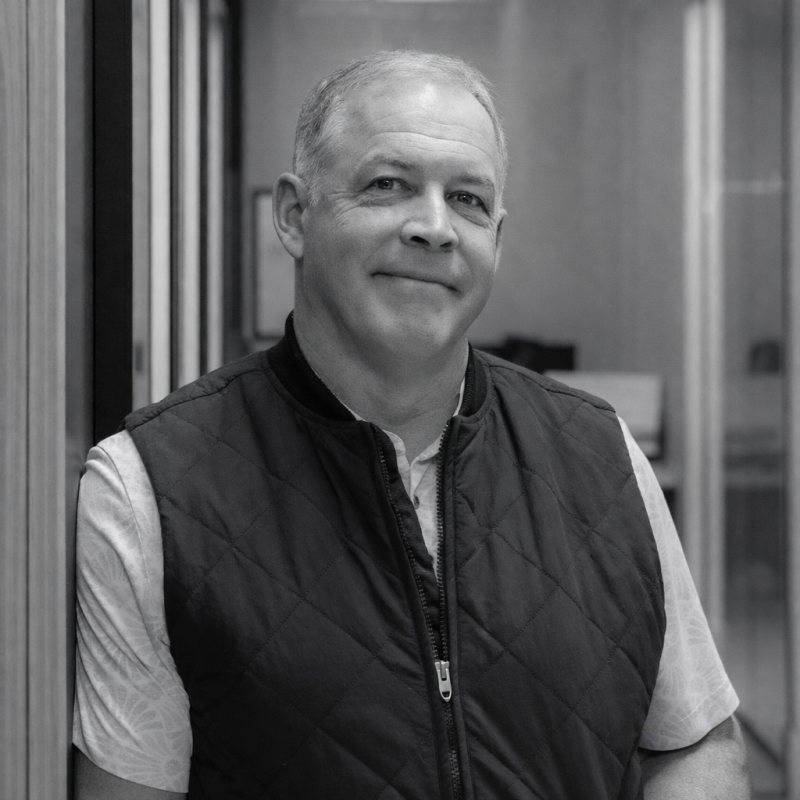
Co-Founder — StrivePoint Advisors
David Wallace is a California native now living in Arizona with his wife and kids. With more than two decades of experience as a CFO and executive leader in the mortgage industry, he has guided multiple lending organizations through growth, capital planning, and complex financial operations. In addition to his advisory work, David serves as a finance professor at Grand Canyon University, where he's committed to helping the next generation build strong financial literacy and practical skills. His clients value his steady judgment, deep industry insight, and ability to make complex financial decisions clear and approachable.
StrivePoint AdvisorsKey questions
What is David Wallace's background in the finance industry?
David Wallace has been in the finance industry since 1993, holding various positions in the C-suite since 1998. He started at Charles Schwab and has worked with several mortgage companies, including American Mortgage Network and Wachovia.
What are the advantages of working with StrivePoint Advisors?
StrivePoint Advisors offers a wealth of knowledge and experience in both residential mortgages and business lending. They have access to a variety of loan options, including hard money loans, and can provide tailored advice based on individual financial situations.
How does being a mortgage broker differ from being a mortgage banker?
As a mortgage broker, David Wallace does not handle underwriting or trading, which reduces pressure and risk compared to being a mortgage banker. Brokers can shop loans to various lenders, providing clients with better pricing and options.
What is the current state of the housing market according to David Wallace?
David believes that the current interest rates around 5% are attractive and advises buyers not to wait for rates to drop further. He emphasizes that real estate remains one of the best investments over time.
What advice does David Wallace give to first-time home buyers?
David encourages first-time home buyers to consider the financial benefits of owning a home versus renting. He helps them analyze their options and find suitable financing solutions.
What types of businesses does David Wallace help with financing?
David assists a variety of businesses with financing, including commercial cleaning companies and nail salons. He helps them reduce debt service and acquire additional companies to grow their operations.
What is David Wallace's approach to ethics in business?
David prioritizes ethics in his business practices and aims to provide honest, straightforward advice to his clients, ensuring they receive fair treatment in all financial dealings.
Full transcript
Show full transcriptHide transcript
Guest share kit
“I started to have a lot more fun, you know, selling and being on the front lines.”
“The pressure relief is a lot higher on the broker side than it is on the banking side.”
“Don't wait for rates to go down to 3%. In my opinion, rates should never have been at 3%.”
“If you're gonna wait around for rates to go down to 4%, it might never happen.”
“I don't think there's any shortage in businesses starting up. There's opportunities abound.”
“I'm just a straight shooter. I'm gonna give you exactly what it is.”
Filed under
More on Phoenix housing and real estate
- Overcoming Real Estate Myths: 30 Years of Phoenix Market Insight with Will Carter
Will Carter · November 11, 2026
- Phoenix Property Care Pros: Justine DuCloux and Brandon Sells on curb appeal and eco-friendly cleaning
Justine DuCloux and Brandon Sells · April 15, 2026
- Salt Media’s Jacob Allumbaugh Discusses Phoenix Real Estate Marketing Innovations
Jacob Allumbaugh · February 25, 2026
- Phoenix real estate trends, affordability and homeownership, with Will Carter
Will Carter · January 6, 2026
Related episodes

Phoenix Property Care Pros: Justine DuCloux and Brandon Sells on curb appeal and eco-friendly cleaning
with Justine DuCloux and Brandon Sells
Phoenix real estate trends, affordability and homeownership, with Will Carter
with Will Carter
Overcoming Real Estate Myths: 30 Years of Phoenix Market Insight with Will Carter
with Will Carter

Salt Media’s Jacob Allumbaugh Discusses Phoenix Real Estate Marketing Innovations
with Jacob Allumbaugh